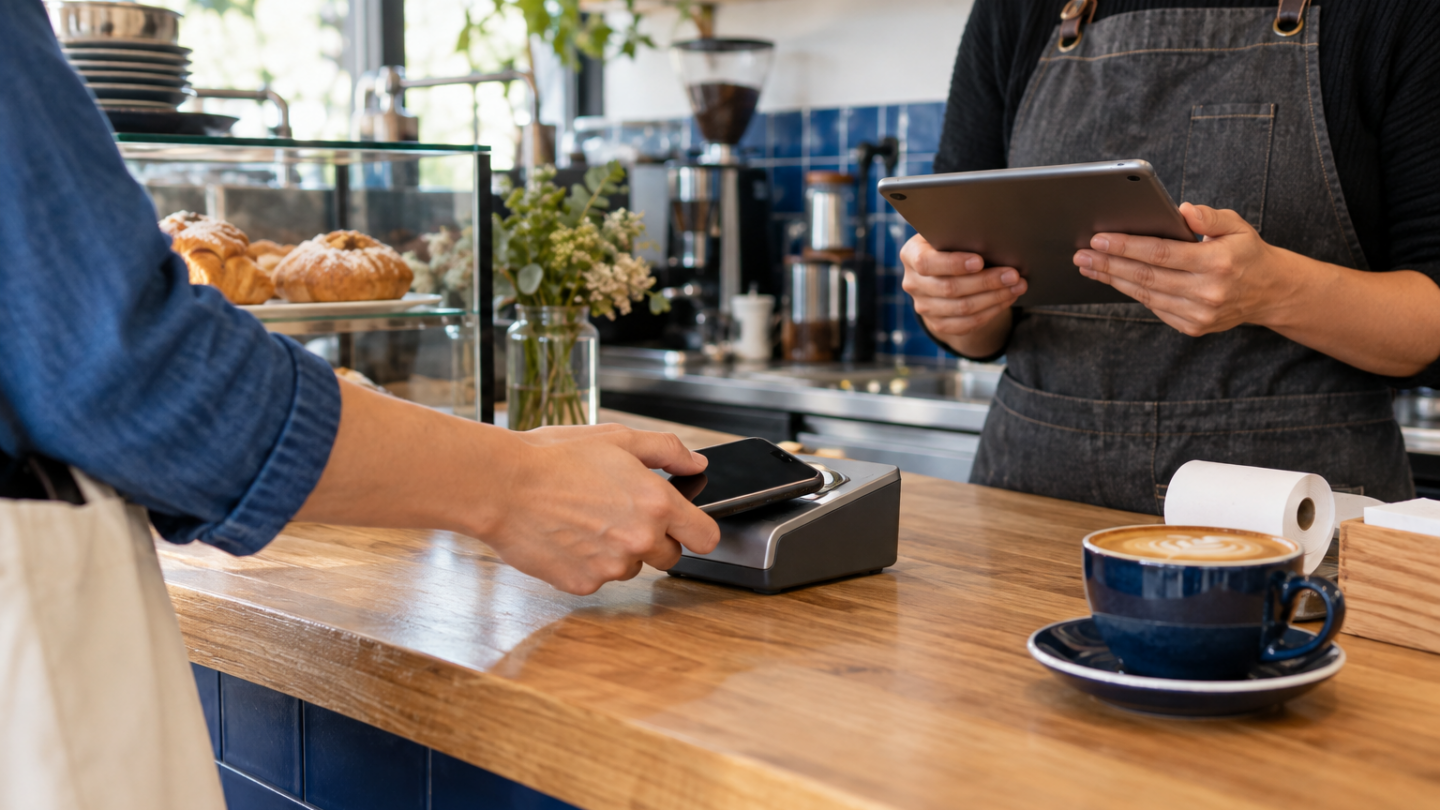
Digital wallets have made card payments faster and changed what customers expect at the checkout. For a business, however, the phone or watch is only the customer-facing layer. The transaction still travels through payment credentials, networks, an acquirer or payment provider, fraud controls and settlement systems, each of which can affect cost.
That means a rise in wallet use does not produce one universal wallet fee. The underlying card type, routing, merchant agreement, transaction channel and provider pricing determine what the merchant pays.
Follow the transaction beneath the wallet
A wallet can store a tokenised version of an eligible debit, credit or charge card. At the terminal or online checkout, the payment is authenticated and processed through an available network. Tokenisation can improve security by reducing exposure of the underlying card number, but it does not remove the network and acquiring costs.
Merchant service fees can include interchange, scheme fees and the acquirer or payment provider’s margin. Pricing may be a blended percentage, an interchange-plus structure, a flat transaction fee or a package including terminal rental and software. The cheapest model depends on average transaction size, card mix and sales channel.
Debit transactions generally cost merchants less than credit transactions on average, but the actual statement can vary. Least-cost routing can direct eligible debit payments through a lower-cost network where enabled, subject to the setup and transaction type.
Compare total acceptance cost
A quoted processing percentage does not capture every charge. Include monthly platform fees, terminal rental, gateway fees, chargebacks, refunds, premium card pricing, cross-border fees and minimum charges. For small transactions, a fixed component can matter more than a small percentage difference.
Online payments often carry different fraud and processing costs from in-person contactless payments. A provider that is competitive at the counter may be expensive for ecommerce, subscriptions or invoices. Splitting the analysis by channel reveals where negotiation or routing changes will have the greatest effect.
Settlement timing affects cash flow. Same-day or next-day settlement can be valuable to a business with tight working capital, but it may come with conditions or price differences. Reliability, reconciliation tools and customer support also have an economic value that is not visible in the transaction rate.
Keep surcharging and pricing rules current
Australian rules limit excessive card surcharges and require attention to the cost of acceptance. If there is no way to pay without a surcharge, the minimum unavoidable surcharge generally needs to be included in the displayed price. Businesses need evidence for the costs used in their calculation.
Payment regulation and card-network rules can change. A surcharge setting that was compliant last year may not remain appropriate after a regulatory change, contract update or new terminal configuration. Merchants should use current ACCC, RBA and provider information rather than copy an old percentage.
Surcharging is only one response to payment cost. A business can negotiate its merchant plan, enable appropriate routing, redesign invoice payment options or incorporate ordinary costs into prices. The customer experience and competitive position matter alongside fee recovery.
Review statements using cost per transaction and cost as a percentage of sales, separated by debit, credit, premium, international and online payments where data allows. Track refunds and chargebacks as well as successful sales. A short monthly dashboard can show whether wallet growth is changing the underlying card mix.
Security remains part of cost control. Strong authentication, staff processes and rapid chargeback evidence can reduce fraud loss and administration. A cheaper provider with weak reconciliation or security support may cost more after incidents are included.
Contract review should include ownership of terminals, minimum terms, cancellation fees, software integrations and portability of transaction data. A low introductory rate can become expensive after it expires, while a proprietary system may increase switching work. Ask for pricing in a format that can be checked against actual monthly volumes and card mix.
Customers also need a clear choice at checkout. Staff training and accurate signage reduce disputes about surcharges or payment acceptance. Receipts should identify the amount charged, and refund procedures should be consistent across wallet, physical card and online transactions.
This article provides general information only and is not personal financial, payments or legal advice. Merchant contracts, network rules and surcharge requirements change, so businesses should confirm the current position for their payment methods.